PTMEG prices shocked the chemical market on June 3, 2026, after falling 16.87% in a single trading session. Such a sharp decline rarely occurs in established industrial chemical markets and immediately drew attention from buyers, traders and manufacturers across the polyurethane value chain.
The price collapse reflects a combination of oversupply and weak downstream demand, particularly from textile and footwear sectors. For procurement teams, the decline creates opportunities to reduce raw material costs, but it also raises important questions about market health, future demand and inventory strategies. Understanding the forces behind this movement can help buyers make better sourcing decisions during the remainder of 2026 and beyond.
What Is PTMEG and Why Does It Matter?
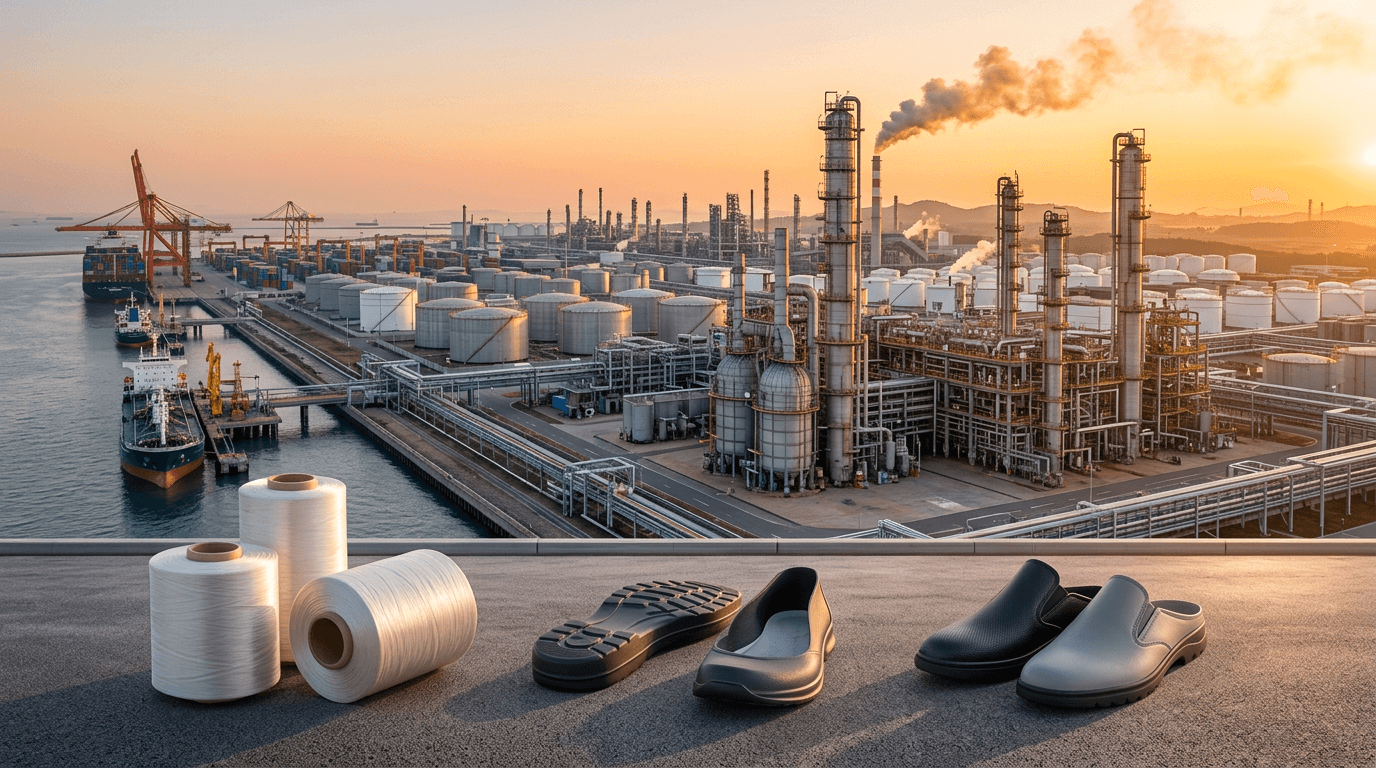
Polytetramethylene ether glycol, commonly known as PTMEG, is a high-value specialty chemical used in the production of elastomeric materials. Manufacturers rely on it as a critical building block for products that require flexibility, durability and elasticity.
PTMEG plays an essential role in spandex fiber production. The material gives spandex its stretch and recovery properties, making it indispensable for sportswear, activewear, swimwear and performance textiles.
The chemical also serves as a key raw material in polyurethane elastomers. These materials appear in industrial components, automotive parts, seals, hoses and numerous engineered products.
Thermoplastic polyurethanes, often referred to as TPUs, represent another major application area. TPUs combine flexibility with durability and support industries ranging from footwear and electronics to medical devices and consumer goods.
Because PTMEG sits near the beginning of several manufacturing chains, changes in its pricing often influence production costs across multiple industries.
Global PTMEG Market Size and Demand in 2026
The global PTMEG market remains heavily connected to the performance of textile and consumer manufacturing sectors.
Asia dominates both production and consumption. Countries such as China, South Korea, Taiwan and India host major spandex manufacturing operations that consume large volumes of PTMEG every year.
Demand growth slowed significantly during 2026. Many textile producers faced weaker order volumes due to cautious consumer spending and softer retail demand in several major markets.
Footwear manufacturing also experienced slower growth than many industry participants expected. Reduced production schedules translated into lower demand for thermoplastic polyurethanes and related materials.
Industrial applications remained relatively stable, but they could not fully offset weakness in textile and footwear markets.
As demand growth slowed, PTMEG inventories increased across parts of the supply chain. This imbalance between production and consumption created conditions that ultimately contributed to the dramatic price decline observed in early June.
For buyers, these developments highlight the importance of monitoring downstream industries rather than focusing solely on chemical production data.
Key Price Drivers and Market Forces Right Now
The most important factor behind the PTMEG price collapse is oversupply.
Production capacity expanded significantly in recent years as manufacturers anticipated continued growth in textiles, apparel and polyurethane applications. Many producers invested in additional capacity to capture expected demand increases.
However, demand failed to grow at the same pace. As economic uncertainty affected consumer spending, apparel brands and manufacturers became more cautious with purchasing and production plans.
Inventory levels gradually increased across the value chain. Suppliers found themselves competing more aggressively to secure sales and maintain production utilization rates.
Margin pressure among spandex manufacturers amplified the problem. Many producers faced rising operational costs while struggling to pass those costs on to customers.
As profitability weakened, manufacturers reduced purchasing volumes and adopted conservative inventory management practices.
The result was a market where available supply significantly exceeded immediate demand requirements. Once selling pressure intensified, prices adjusted rapidly.
The scale of the single-day decline indicates that market participants were responding not only to current conditions but also to expectations of continued weakness.
Top Producing and Exporting Countries
China remains the dominant force in the PTMEG market.
The country hosts a substantial share of global PTMEG production capacity and supports a large domestic spandex manufacturing industry. Chinese producers influence pricing trends across Asia and often shape broader market sentiment.
South Korea plays an important role as both a producer and technology leader within specialty chemical markets. Its manufacturers supply PTMEG to regional and international customers.
Taiwan maintains strong connections to the textile and synthetic fiber sectors. Many manufacturers within the region consume PTMEG directly through integrated production chains.
Japan continues to participate in higher-value specialty applications where quality and performance requirements remain particularly demanding.
India has expanded its presence within textile manufacturing and polyurethane processing. As industrial capabilities continue growing, the country's influence on regional demand is expected to increase.
These production centers create a highly competitive marketplace. When demand weakens, suppliers across the region often compete aggressively on price to maintain market share.
Applications and Who Buys PTMEG?
The largest PTMEG consumers operate within the textile industry.
Spandex manufacturers rely on PTMEG as a primary feedstock for elastic fibers used in apparel and performance textiles. Demand from this sector directly influences overall market conditions.
Sportswear brands, activewear manufacturers and fashion producers ultimately drive much of this consumption. Changes in retail demand often move through the supply chain and eventually affect PTMEG purchasing patterns.
Footwear manufacturers represent another important customer group. Thermoplastic polyurethanes produced from PTMEG contribute to soles, cushioning systems and performance components.
Automotive suppliers use polyurethane elastomers in specialized parts that require flexibility and wear resistance. These applications provide a stable source of industrial demand.
Medical device manufacturers also consume smaller volumes through specialty polyurethane applications where durability and biocompatibility matter.
Although PTMEG serves diverse industries, the textile and footwear sectors remain the primary demand engines. Current weakness in these markets explains much of the recent pricing pressure.
Risks, Challenges and Regulatory Issues
The current PTMEG market faces several challenges beyond immediate supply-demand imbalances.
Persistent oversupply remains the biggest concern. If producers continue operating at high utilization rates while demand remains weak, downward pressure on prices may continue.
Margin compression across the spandex industry presents another challenge. Manufacturers already face intense competition and may continue reducing procurement volumes until profitability improves.
Global consumer spending trends will also influence market direction. Weak retail demand often translates into lower orders for apparel and footwear manufacturers.
Environmental regulations continue evolving across major production regions. Chemical producers must invest in cleaner operations, emissions control systems and sustainability initiatives.
Trade policies and international market conditions may create additional uncertainty. Changes in tariffs, logistics costs or export regulations could affect competitiveness and sourcing decisions.
Procurement teams should monitor these risks carefully when planning purchasing strategies for the coming quarters.
Outlook for 2027 and Beyond
The long-term outlook for PTMEG remains tied to growth in performance textiles, polyurethane applications and advanced materials.
Demand for athletic apparel and technical textiles should continue expanding over time. These markets benefit from consumer interest in comfort, performance and functional fabrics.
Footwear innovation may also support future PTMEG consumption. Manufacturers increasingly use advanced polymer materials to improve product performance and durability.
However, short-term recovery depends on restoring balance between supply and demand.
If producers reduce operating rates or delay capacity expansions, market conditions could gradually stabilize. Stronger consumer spending and improved manufacturing activity would also support demand growth.
Procurement teams should expect continued volatility during the near term. Markets rarely recover immediately after sharp price corrections, particularly when structural oversupply remains a factor.
Despite current challenges, PTMEG remains a strategically important material with strong long-term industrial relevance.
What Polyurethane Buyers Should Do Now
The 16.87% decline in PTMEG prices reflects more than a temporary market fluctuation. It highlights growing pressure within textile, footwear and polyurethane supply chains as demand struggles to keep pace with available production capacity.
For procurement teams, the current environment presents opportunities to secure favorable pricing and negotiate long-term supply agreements. Lower raw material costs can improve margins for manufacturers that depend on polyurethane and spandex production.
At the same time, buyers should remain cautious about assuming that low prices alone indicate a healthy market. Weak downstream demand continues to create uncertainty, and further volatility remains possible if inventories stay elevated.
Monitoring textile production, footwear manufacturing activity and spandex market conditions will remain essential throughout the coming months. Companies that combine strategic sourcing with careful market analysis will be best positioned to benefit from changing conditions.