Borax Decahydrate (Technical Grade) - Argentina CAS: 1303-96-4
Borax Decahydrate (Technical Grade) - Argentina CAS: 1303-96-4
Commodity chemical markets close H1 2026 after an extraordinary period of price swings, supply disruptions and policy changes. This review highlights key movements in crude oil, urea, methanol, Gulf exports and procurement priorities for H2 planning.
GCC construction chemical demand closes H1 2026 having been substantially suppressed by project delays across UAE
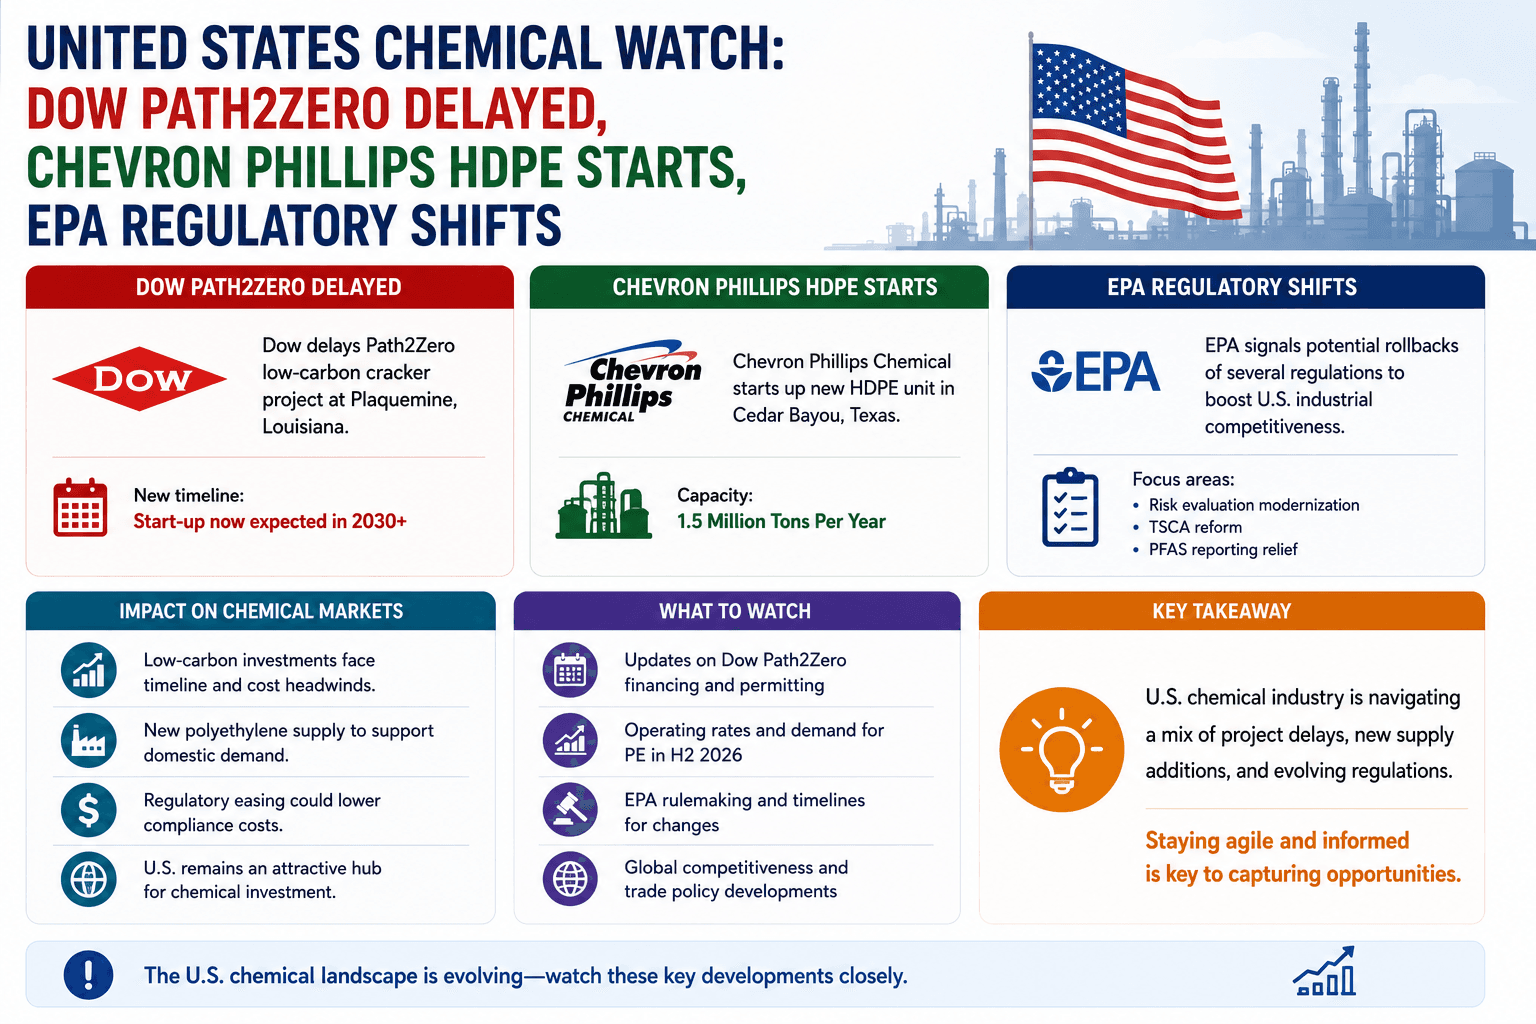
Europe’s chemical industry has lost 37 million tonnes of production capacity since 2022 as plant closures accelerate across the region. For global buyers, shrinking European supply is becoming a major long-term sourcing risk that extends far beyond Europe itself.
By 2026 the sodium bicarbonate market will see a dip in industrial use driven by construction sector softness, while food‑grade demand stays flat. Europe’s supply chain faces energy‑price pressure, reshaping supplier dynamics and pricing strategies.
The world's largest chemical companies generated more than $400 billion in combined revenue in 2026. BASF remains the industry leader, Sinopec demonstrates China's manufacturing scale and Wanhua Chemical continues its rapid ascent as a global specialty chemicals powerhouse.
The latest intelligence report from June 19, 2026 outlines ten pivotal developments reshaping procurement and trade in the chemical sector. From the Hormuz Memorandum of Understanding to surging methanol futures, discover how SCFI index movements and ChemCon Asia insights are guiding strategic decisions.
We're committed to your privacy. Tradeasia uses the information you provide to us to contact you about our relevant content, products, and services. For more information, check out our privacy policy.