Urea (Granular) - Egypt CAS: 57-13-6
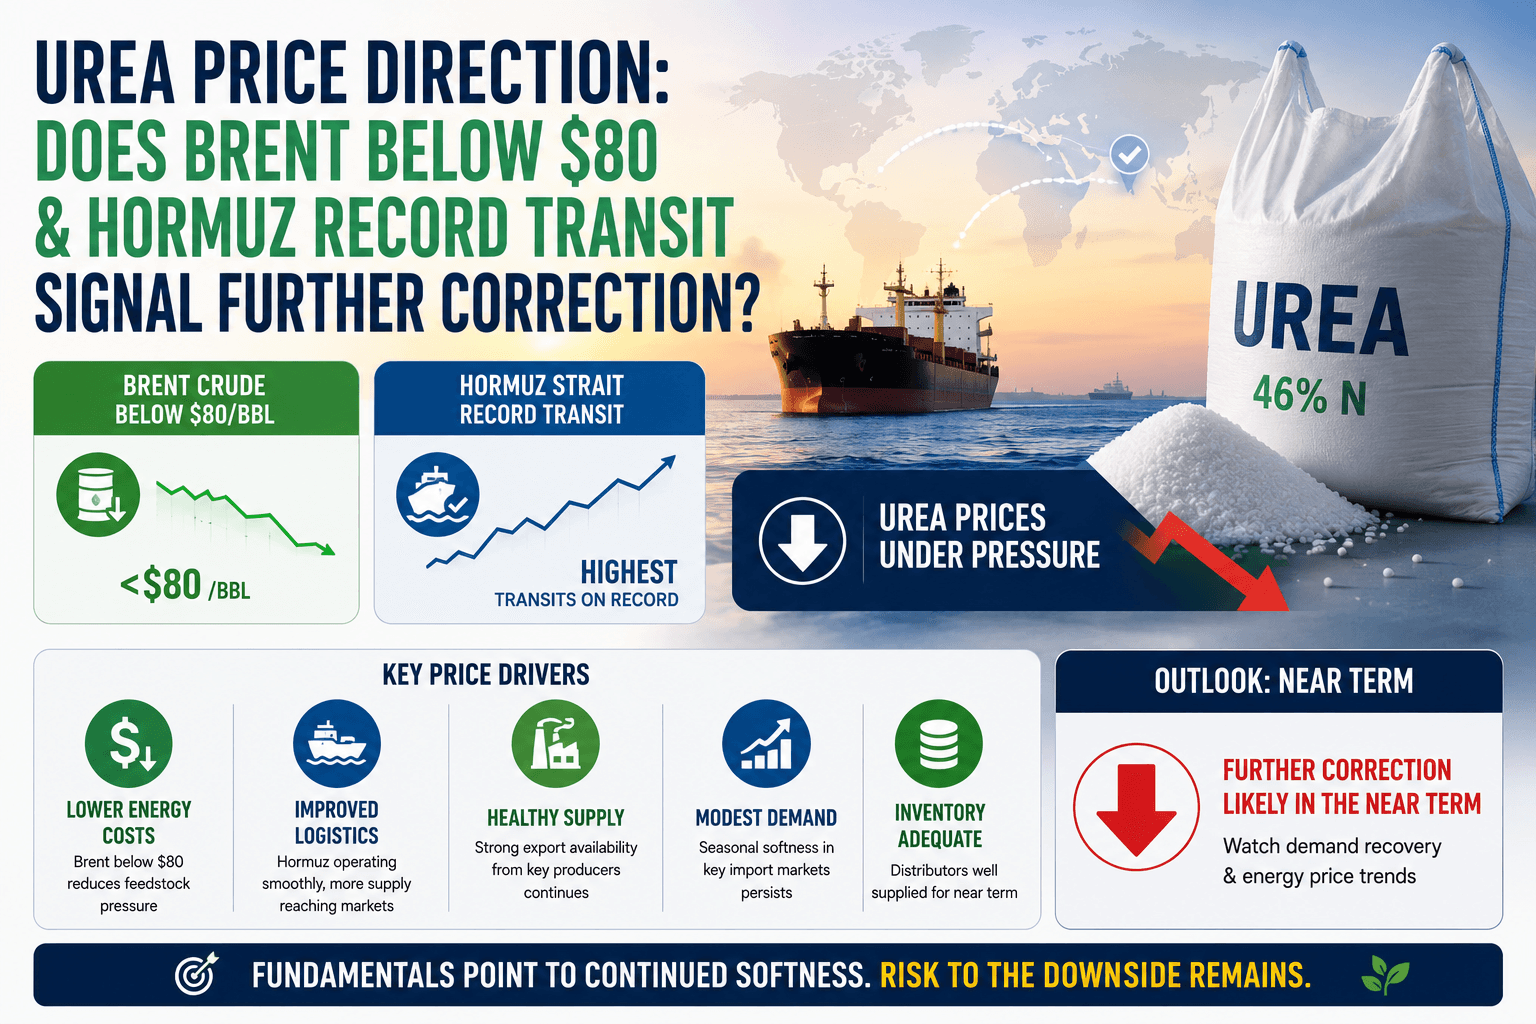
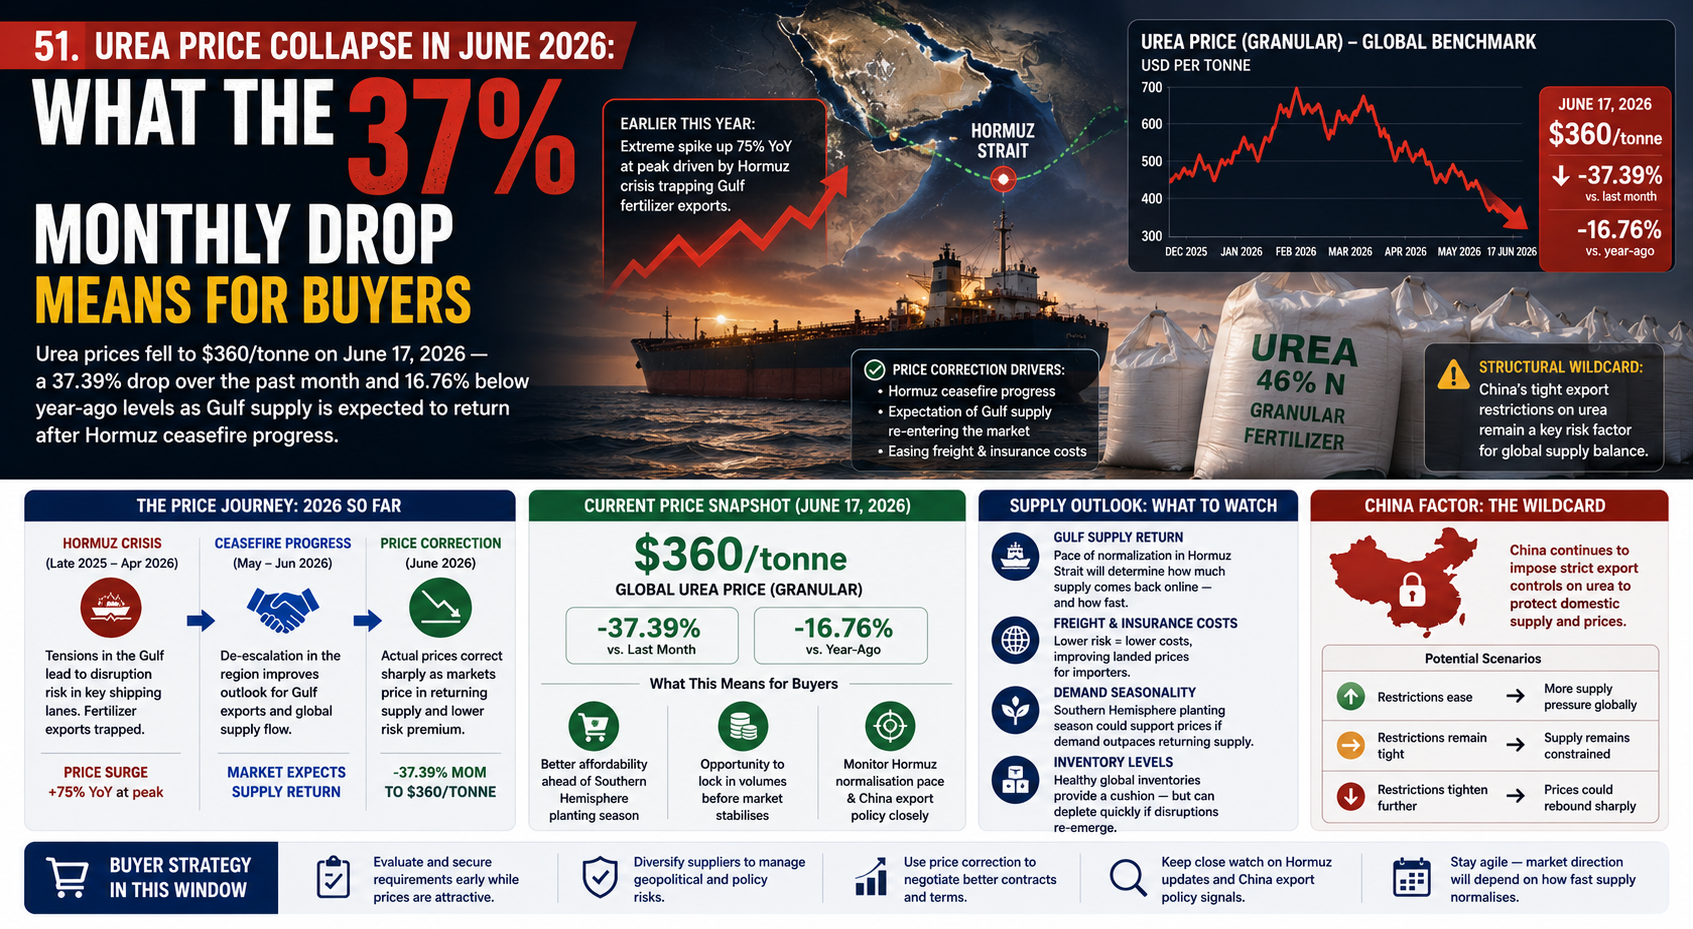
Urea prices have already fallen 36% from April highs, but improving Hormuz shipping and lower Brent crude suggest only modest further correction ahead. For fertilizer buyers, the strongest buying opportunity may already be unfolding before Q3 market stabilization begins.
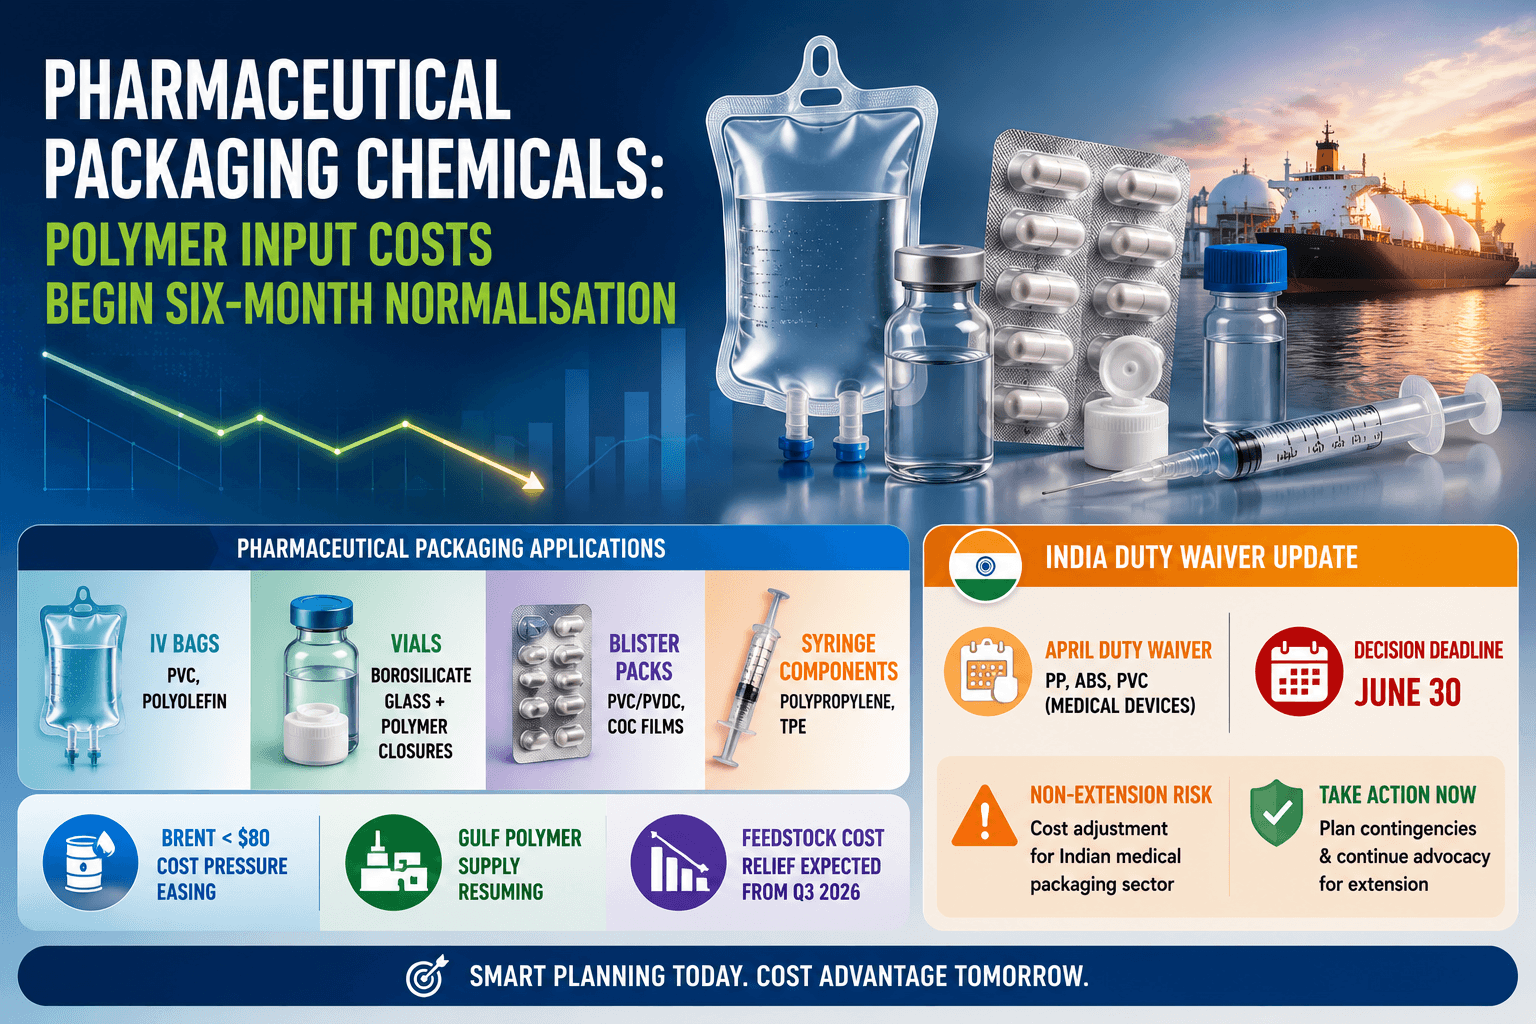
Pharmaceutical packaging costs are beginning to ease as Gulf polymer supply recovers and crude prices fall, but India’s June 30 duty waiver decision could quickly reverse cost relief for manufacturers dependent on Indian packaging components.
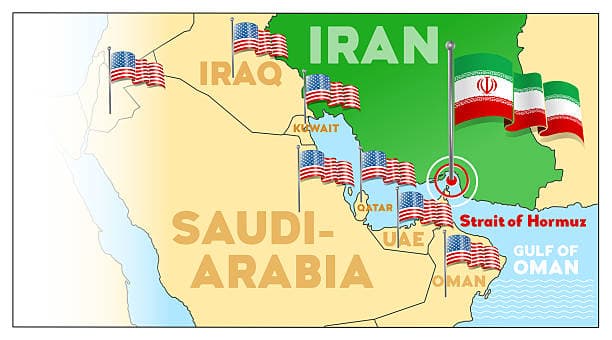
In June 2026, the US chemical scene was jolted by a strategic Hormuz MOU, the disruptive impact of Hurricane Arthur, the landmark Olin‑Huntsman merger, and the sudden INEOS Styrolution plant shutdown. These events reshaped supply chains and market dynamics across North America.
Pharmaceutical-grade glycerin is experiencing sustained price pressure in 2026 as disruptions across the global oleochemical supply chain raise production costs. Pharmaceutical and personal care buyers are increasingly prioritizing supply security as the premium between pharma and technical-grade glycerin widens.
Morocco’s OCP Group has become the most important phosphate fertilizer supplier in 2026 as Hormuz disruptions restrict Gulf exports. Buyers are increasingly treating OCP pricing as the new short-term benchmark for global phosphate markets.
Corn starch prices firmed across North America, Europe, and Asia in Q1 2026. Track mid-May supply conditions, regional demand, and sourcing strategy
We're committed to your privacy. Tradeasia uses the information you provide to us to contact you about our relevant content, products, and services. For more information, check out our privacy policy.